Applying for a loan can feel stressful, especially when approval criteria seem unclear. Many applicants believe approval depends on a single factor, such as income or credit score.
In reality, banks evaluate multiple elements before making a decision. Understanding what lenders actually look at can significantly increase your chances of approval.
Knowing these criteria also helps you avoid applying for loans you are not ready for yet.
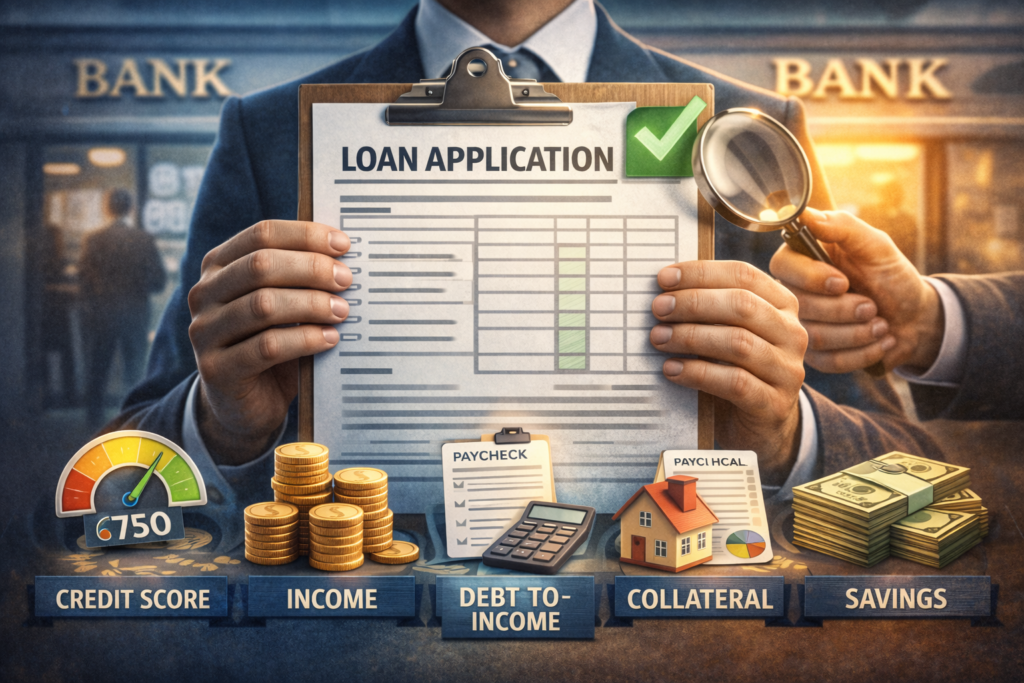
Credit History and Credit Score
Credit history is one of the first things banks analyze. It shows how you have managed debt in the past.
Your credit score summarizes this history into a number. It reflects payment behavior, outstanding debt, and credit usage.
A higher score signals reliability, while missed payments or defaults raise red flags for lenders.
Payment Behavior Matters More Than You Think
Banks pay close attention to whether you pay bills on time. Even small delays can affect approval.
Consistent, on-time payments demonstrate financial responsibility. This behavior builds trust with lenders.
A perfect score is not always required, but a stable payment record is essential.
Income Stability and Employment History
Income alone is not enough. Banks want to see stability and predictability.
A steady income from regular employment reassures lenders that you can meet monthly payments.
Frequent job changes or irregular income may raise concerns, even if earnings are high.
Debt-to-Income Ratio
Debt-to-income ratio shows how much of your income is already committed to debt.
Banks calculate this by comparing monthly debt payments to gross monthly income.
A lower ratio indicates financial flexibility, while a high ratio suggests higher risk.
Existing Financial Obligations
Lenders look at all current obligations, including credit cards, loans, and other liabilities.
Even unused credit lines can influence approval, as they represent potential future debt.
Managing existing obligations responsibly improves your overall financial profile.
Loan Purpose and Type
Banks consider why you are requesting the loan. Different purposes carry different risk levels.
Loans for education or transportation are often viewed as investments. Unclear or risky purposes may face stricter evaluation.
The type of loan also matters. Secured loans are generally easier to approve than unsecured ones.
Collateral and Guarantees
For secured loans, collateral plays a major role. It reduces the bank’s risk.
Assets such as vehicles or property provide assurance that the loan can be recovered if needed.
Strong collateral can sometimes offset weaker credit factors.
Loan Amount and Repayment Term
Borrowing more than necessary can hurt your chances. Banks assess whether the amount requested is reasonable.
Longer repayment terms lower monthly payments but increase total risk.
A balanced loan structure shows careful planning and financial awareness.
Savings and Financial Reserves
Savings indicate financial discipline. They show that you can handle unexpected expenses.
Banks view emergency funds as a safety net that protects loan repayment.
Applicants with savings are often considered more resilient and reliable.
Banking Relationship and History
Your relationship with the bank can influence approval. Long-term customers may benefit from trust and familiarity.
Positive account behavior, such as avoiding overdrafts, strengthens your profile.
While not decisive, a good banking history can be a supportive factor.
Documentation and Accuracy
Incomplete or inaccurate information can delay or prevent approval.
Banks verify all details, including income, employment, and identification.
Clear and honest documentation speeds up the process and builds credibility.
Risk Assessment and Internal Policies
Each bank follows internal risk policies. These rules determine acceptable risk levels.
Approval is not always personal. Sometimes it reflects broader economic or institutional criteria.
Understanding this helps manage expectations and reduce frustration.
How to Improve Your Chances Before Applying
Preparation makes a difference. Review your credit report and correct errors.
Reduce outstanding debt where possible and avoid new credit before applying.
A stronger financial profile increases approval odds and may secure better terms.
What to Do If You Are Denied
Loan denial is not the end. Banks often provide reasons for rejection.
Use this feedback to improve your financial situation before reapplying.
Patience and preparation turn rejection into an opportunity for growth.
Conclusion
Loan approval is based on a complete financial picture, not a single number.
Banks evaluate credit behavior, income stability, debt levels, and overall financial responsibility.
Understanding what lenders actually look at empowers you to prepare strategically. With the right approach, loan approval becomes a realistic and achievable goal rather than a mystery.